PM Jan Dhan Yojana 2026: Benefits, ₹10,000 Overdraft, Documents and Bank Camps
Read in another language:
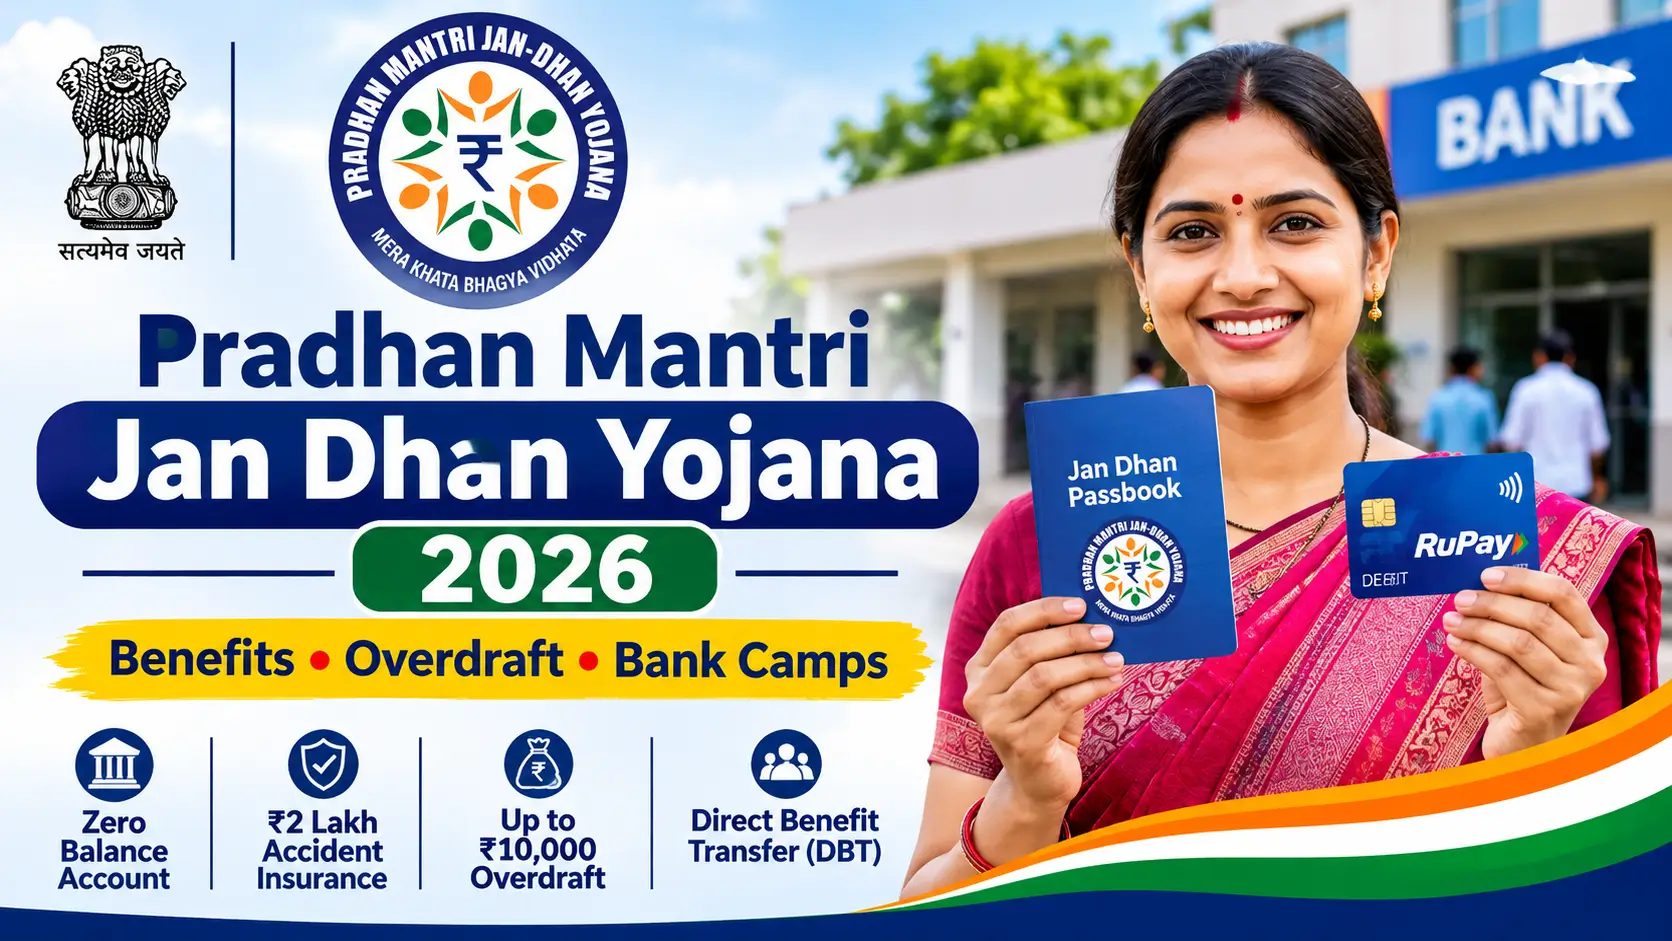
The Pradhan Mantri Jan Dhan Yojana (PMJDY) is a financial inclusion scheme launched by the Government of India to provide basic banking services to people who do not have a bank account. Eligible individuals can open a zero-minimum-balance account and access services such as deposits, a RuPay debit card, Direct Benefit Transfer (DBT) and an overdraft facility of up to ₹10,000, subject to the applicable conditions.
A nationwide Financial Inclusion Saturation Campaign is currently underway. From 21 October to 31 December 2026, banks are organising camps across 2.70 lakh Gram Panchayats and Urban Local Bodies (ULBs). These camps aim to help eligible people open bank accounts, complete re-KYC, enrol in financial security schemes and access other banking services.
However, a Jan Dhan account does not automatically guarantee a ₹10,000 overdraft, an insurance claim or a government payment. Each benefit has its own eligibility requirements.
This guide explains the latest PM Jan Dhan Yojana update, account-opening process, required documents, overdraft rules, RuPay insurance and how to find a bank camp.
PM Jan Dhan Yojana Latest Update 2026: Financial Inclusion Camps
The Department of Financial Services (DFS), Ministry of Finance, announced a nationwide Financial Inclusion Saturation Campaign on 19 October 2026.
The campaign runs from 21 October to 31 December 2026 and covers 2.70 lakh Gram Panchayats and Urban Local Bodies.
During this period, participating banks are conducting camps for:
- Opening PMJDY accounts for eligible unbanked individuals.
- Completing re-KYC of existing PMJDY and other savings accounts.
- Aadhaar seeding for eligible insurance scheme beneficiaries.
- Enrolment under Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY).
- Enrolment under Pradhan Mantri Suraksha Bima Yojana (PMSBY).
- Enrolment under Atal Pension Yojana (APY).
- Updating nominations in eligible savings accounts and locker facilities.
- Generating C-KYC IDs and providing other financial inclusion services.
- Awareness sessions on digital fraud prevention.
- Assistance under the “Aapki Poonji, Aapka Adhikar” initiative for unclaimed financial assets.
- Sourcing Kisan Credit Card applications for eligible PM-Kisan beneficiaries and promoting crop insurance enrolment.
The campaign is intended to improve access to financial services for eligible individuals who have not yet been covered.
How to find a PMJDY camp near you: Contact your bank branch, local Bank Mitra, Gram Panchayat office or Urban Local Body. Ask for the date, location and services available at the next financial inclusion camp.
PMJDY Bank Camps in Odisha
The nationwide financial inclusion campaign also covers Odisha. However, a separate statewide district-wise or panchayat-wise camp schedule was not available in the official sources checked for this article.
Residents of Odisha should contact their bank branch, local Bank Mitra or Gram Panchayat for information about nearby camps.
Official update: PIB – Financial Inclusion Saturation Campaign( https://www.pib.gov.in/PressReleasePage.aspx?PRID=2325230)
PM Jan Dhan Yojana 2026: Overview
| Particular | Details |
|---|---|
| Full name | Pradhan Mantri Jan Dhan Yojana |
| Short name | PMJDY |
| Launch date | 28 August 2014 |
| Ministry | Ministry of Finance |
| Nodal department | Department of Financial Services |
| Account type | Basic Savings Bank Deposit Account (BSBD) |
| Minimum balance | Not required |
| Maximum overdraft | Up to ₹10,000, subject to eligibility |
| RuPay debit card | Available to eligible account holders |
| Accident insurance | Up to ₹2 lakh for eligible RuPay PMJDY cards |
| Account opening location | Bank branch or Bank Mitra |
| Official website | pmjdy.gov.in |
PMJDY Statistics 2026
According to the Ministry of Finance, PMJDY had achieved the following milestones as of 19 August 2026.
| Particular | Official figure |
|---|---|
| Total PMJDY accounts | 59.09 crore |
| Total deposits | ₹3,16,514 crore |
| Average deposit per account | ₹5,356 |
| RuPay cards issued | 41.29 crore |
| Women account holders | 32.92 crore |
| Rural and semi-urban accounts | 45.95 crore |
Data date: 19 August 2026.
These are historical figures, not live account statistics. The number of accounts, deposits and RuPay cards may have changed since the reported date.
Source: PIB – PMJDY Completes 12 Years (https://www.pib.gov.in/PressReleseDetailm.aspx?PRID=2303643)
Benefits of PM Jan Dhan Yojana
PMJDY provides access to basic banking services and selected financial security schemes. The main benefits are explained below.
1. Zero Minimum Balance Account
A PMJDY account does not require a minimum balance. Eligible account holders can maintain a zero balance without losing the account simply because they have no money deposited.
2. RuPay Debit Card
Eligible account holders receive a RuPay debit card that can be used for permitted ATM, point-of-sale and digital banking transactions.
The card may also provide personal accident insurance under the applicable RuPay insurance policy.
3. Accident Insurance Cover
Eligible RuPay PMJDY debit cards carry personal accident insurance cover.
- Up to ₹1 lakh for eligible older PMJDY RuPay cards.
- Up to ₹2 lakh for eligible PMJDY RuPay cards issued for accounts opened after 28 August 2018.
This is accident insurance, not a general life insurance benefit or a guaranteed cash payment.
The claim is subject to the applicable insurance policy, eligibility requirements, transaction conditions and supporting documents.
4. Overdraft Facility up to ₹10,000
Eligible account holders may receive an overdraft facility of up to ₹10,000.
An overdraft allows the account holder to withdraw more money than the available account balance, within the approved limit.
It is a credit facility, not a grant or subsidy. The amount used must be repaid according to the bank’s terms.
5. Direct Benefit Transfer (DBT)
PMJDY accounts can be used to receive eligible government benefits and subsidies through Direct Benefit Transfer.
However, opening a Jan Dhan account does not guarantee payment under every government scheme. The beneficiary must meet the eligibility conditions of the scheme concerned.
6. Access to Insurance and Pension Schemes
Eligible account holders can enrol in or access financial security schemes such as:
- Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY)
- Pradhan Mantri Suraksha Bima Yojana (PMSBY)
- Atal Pension Yojana (APY)
These schemes have separate eligibility conditions, contribution requirements and benefits.
7. Interest on Deposits
Money deposited in a PMJDY account earns interest at the savings account rate applicable to the bank.
The interest rate is determined by the bank and may differ between banks.
PMJDY Eligibility: Who Can Open a Jan Dhan Account?
PMJDY is intended to provide banking access to people who do not already have a bank account.
The main eligibility points are:
- Unbanked individuals: The scheme focuses on people who do not have an existing bank account.
- Adults: Eligible unbanked adults can open an account under the applicable banking rules.
- Minors: Minors above 10 years may be eligible to open an account under the bank’s rules. Operating conditions may apply.
- Joint accounts: Joint account opening is permitted under applicable banking rules.
- Overdraft eligibility: The overdraft facility has a separate age limit of 18 to 65 years.
If you already have a regular savings account, do not assume that you can open another PMJDY account simply to obtain additional benefits.
Existing account holders should ask their bank about the benefits and RuPay insurance coverage applicable to their existing account.
Documents Required for PM Jan Dhan Yojana
The documents required depend on your KYC status and the bank where you apply.
If You Have Aadhaar
Aadhaar or proof of possession of Aadhaar can be used for account opening, subject to applicable KYC rules.
If your current address is different from the address mentioned in Aadhaar, the bank may accept self-certification of your present address, as permitted under the applicable rules.
If You Do Not Have Aadhaar
You may provide an officially valid document accepted under the applicable KYC rules.
Examples include:
- Passport
- Driving licence
- Voter ID card
- NREGA job card
- Letter issued by the National Population Register
The bank will confirm which documents are acceptable for your account-opening application.
If You Do Not Have an Officially Valid Document
RBI rules permit the opening of a Small Account using a self-attested photograph and signature or thumb impression in the presence of a bank official.
Small Accounts have specific restrictions.
| Limit | Small Account rule |
|---|---|
| Total credits | Up to ₹1 lakh in a financial year |
| Withdrawals and transfers | Up to ₹10,000 per month |
| Maximum balance | ₹50,000 at any time |
| Initial validity | 12 months |
The account may continue for another 12 months if the account holder provides evidence of having applied for an officially valid document within the required period.
These are Small Account rules under RBI’s KYC framework. They should not be confused with the standard terms of every PMJDY account.
Confirm the latest requirements with your bank before applying.
Source: RBI – Master Direction on KYC (https://rbi.org.in/scripts/BS_ViewMasDirections.aspx?id=13014)
How to Open a Jan Dhan Account
Eligible individuals can open a PMJDY account at a participating bank branch or through a Bank Mitra (Business Correspondent).
Follow these steps:
- Visit your nearest bank branch or Bank Mitra outlet.
- Ask for the PMJDY or Basic Savings Bank Deposit Account opening form.
- Download the form from the official PMJDY website, if required.
- Fill in your personal details and provide the required KYC documents.
- Add a nominee, where applicable.
- Submit the application form and supporting documents.
- The bank will verify your details and process the account opening.
- Collect your passbook and RuPay debit card, if issued.
Keep your account details and debit card PIN secure.
Important: Do not pay an unauthorised person to open a Jan Dhan account. If someone demands money for a government benefit or account activation, verify the request with your bank.
How the ₹10,000 Jan Dhan Overdraft Works
The PMJDY overdraft facility is a credit facility linked to an eligible account.
For example, if your bank approves an overdraft of ₹5,000 and your account balance is zero, you may be able to withdraw up to the approved amount.
The amount used must be repaid according to the bank’s terms.
Important Overdraft Conditions
The scheme provides an overdraft facility of up to ₹10,000.
The main conditions include:
- The maximum overdraft limit is ₹10,000.
- The overdraft facility is generally available after six months of satisfactory account operation, subject to eligibility.
- The age limit for availing the overdraft is 18 to 65 years.
- Only one account holder per household can avail the facility.
- The bank decides the actual amount sanctioned.
- No conditions are attached to the overdraft amount up to ₹2,000 under the 2018 scheme revision.
The overdraft limit was increased from ₹5,000 to ₹10,000 in September 2018.
Is Interest Charged on the Overdraft?
An overdraft is a loan, and interest or other applicable charges may apply.
The exact interest rate, repayment period and other conditions depend on the bank’s applicable terms.
Before using the facility, ask your bank about:
- The approved overdraft amount
- Interest rate
- Repayment schedule
- Applicable charges
- Consequences of delayed repayment
Official source: PIB – PMJDY Overdraft Revision (https://pib.gov.in/PressReleasePage.aspx?PRID=1545089)
RuPay Debit Card Accident Insurance: Eligibility and Claim Process
PMJDY RuPay debit cards carry accident insurance cover, subject to the applicable policy.
For eligible cards, the cover is generally:
- ₹1 lakh for eligible older PMJDY cards.
- ₹2 lakh for eligible PMJDY cards issued for accounts opened after 28 August 2018.
The insurance is intended for specified accidental death or permanent disability events. It does not cover every type of death or medical condition.
RuPay Insurance Transaction Requirement
The applicable RuPay insurance policy requires at least one successful qualifying financial or non-financial transaction through an eligible channel within 90 days before the accident, including the accident date.
The transaction must meet the conditions specified in the relevant policy.
Do not assume that every UPI payment or ATM withdrawal qualifies. Check the current policy with your card-issuing bank.
How to Make a RuPay Insurance Claim
If an eligible accident occurs:
- Inform the bank branch that issued the RuPay card.
- Ask for the applicable PMJDY RuPay accident insurance claim form.
- Obtain the required list of supporting documents.
- Submit the claim through the bank according to the policy procedure.
- Keep copies of the submitted documents and acknowledgement.
The claim is assessed by the insurer under the applicable policy. The insurance amount is not automatically credited to every account holder.
Official reference: NPCI – RuPay Insurance Programme ( https://www.npci.org.in/)
PMJDY Re-KYC and Inactive Accounts
KYC stands for Know Your Customer. Banks use it to verify the identity and address of account holders.
Re-KYC is the process of updating or confirming these details when required.
If your Jan Dhan account has become inactive or your KYC details need updating, contact your bank branch.
During the Financial Inclusion Saturation Campaign running until 31 December 2026, banks are also conducting re-KYC and other account-related activities.
You may need to carry:
- Aadhaar or another accepted KYC document
- Bank passbook
- RuPay debit card, if available
- Updated mobile number
- Any additional document requested by the bank
Ask the bank whether your account is inactive, inoperative or simply requires KYC updating. These situations may require different procedures.
Safety Tips During Bank Camps
- Never share your OTP or debit card PIN.
- Do not hand your card to an unauthorised person.
- Avoid sharing full card details through phone calls or messages.
- Do not pay a fee to receive a government benefit.
- Attend only camps confirmed by your bank or local administration.
Common PM Jan Dhan Yojana Problems and Solutions
| Problem | What you should do |
|---|---|
| Bank account opening application is rejected | Ask the bank for the reason and the required correction. |
| RuPay debit card has not arrived | Contact the issuing branch and check the card status. |
| Account has become inactive | Visit the bank for reactivation and KYC guidance. |
| Government DBT payment is delayed | Check your scheme eligibility and bank account details. |
| Aadhaar is not linked | Ask the bank about Aadhaar seeding and authentication. |
| Overdraft is not approved | Ask the bank to check your account operation and eligibility. |
| Accident insurance claim is pending | Contact the card-issuing branch and confirm the claim documents. |
Related Guides
If you are checking a government payment in Odisha, the following guides may also help:
- Subhadra Yojana Face e-KYC
- Subhadra Yojana Rejected List and Fixes
- Subhadra Yojana Application Status
- How to Apply for Subhadra Yojana Online
- Ama Shasana WhatsApp Number and Helpline
Official PM Jan Dhan Yojana Links
Use the following official websites to verify scheme information.
| Purpose | Official link |
|---|---|
| PMJDY portal | pmjdy.gov.in |
| PMJDY scheme benefits | Official scheme page (https://pmjdy.gov.in/scheme) |
| Account opening form | Download PMJDY form (https://pmjdy.gov.in/files/Forms/account-opening/English.pdf) |
| Department of Financial Services | financialservices.gov.in |
| Latest financial inclusion campaign | PIB release (https://www.pib.gov.in/PressReleasePage.aspx?PRID=2325230) |
| 2018 overdraft revision | PIB Cabinet release (https://pib.gov.in/PressReleasePage.aspx?PRID=1545089) |
| RBI KYC rules | RBI Master Direction (https://rbi.org.in/scripts/BS_ViewMasDirections.aspx?id=13014) |
The PMJDY portal also provides official scheme information and contact details.
Frequently Asked Questions
1. What is PM Jan Dhan Yojana 2026?
PM Jan Dhan Yojana is a national financial inclusion scheme launched on 28 August 2014. It provides eligible unbanked individuals with access to a basic bank account, RuPay debit card, DBT and other financial services.
2. Is ₹10,000 available free under Jan Dhan Yojana?
No. ₹10,000 is the maximum overdraft facility available to eligible account holders. It is a credit facility that must be repaid.
3. Does every Jan Dhan account holder receive ₹2 lakh?
No. ₹2 lakh is the accident insurance cover available on eligible RuPay PMJDY debit cards issued for accounts opened after 28 August 2018. It is not a cash payment.
4. Is Aadhaar compulsory for opening a Jan Dhan account?
Aadhaar is an accepted document for account opening. Other officially valid documents may also be accepted. Small Accounts may be opened under applicable RBI rules if a person does not have the required documents.
5. Can I open a Jan Dhan account if I already have a bank account?
PMJDY focuses on providing accounts to unbanked individuals. If you already have a bank account, ask your bank about the benefits and insurance coverage applicable to your existing account.
6. What is the age limit for a Jan Dhan account?
Eligible adults can open an account under the applicable banking rules. Minors above 10 years may also be eligible under the relevant account-opening rules. The overdraft facility has a separate age limit of 18 to 65 years.
7. When will PMJDY bank camps end in 2026?
The nationwide Financial Inclusion Saturation Campaign runs from 21 October to 31 December 2026.
8. How can I find a Jan Dhan bank camp in Odisha?
Contact your bank branch, Bank Mitra, Gram Panchayat or local administration. A separate Odisha-wide camp schedule was not available in the official sources checked for this article.
9. Does a Jan Dhan account guarantee government scheme payments?
No. DBT payments depend on the eligibility conditions of the relevant government scheme. An account alone does not guarantee a payment.
10. How can I check my Jan Dhan account details?
Visit your bank branch or use the bank’s authorised banking services. The official PMJDY portal also provides scheme information and links to relevant services.
Disclaimer: This website is not affiliated with any government department. The information is provided for general guidance. PMJDY benefits, insurance coverage, overdraft eligibility and banking procedures are subject to official scheme guidelines and the applicable bank or insurance policy. Please verify the latest details through official sources before taking any action.